
Stop Relenting: Five Steps and Scripts for Money Boundaries

Use scripts, a five step process, the Money Circle, and a pause rule to set money boundaries that stick. Daily exercises and 30 day toolkit.
Stop Relenting: Five Steps and Scripts for Money Boundaries
Money boundaries are specific limits and agreements about how you earn, spend, save, lend, share, and talk about money, both with yourself and with other people. The fastest way to start is to pick one measurable rule tied to a real goal: a dollar cap, a lending policy, or a set response time for requests. Scripts and a full framework follow, so you can turn that rule into a conversation you can actually have.
TL;DR:
- Clear, measurable money boundaries prevent resentment and financial misunderstandings, especially in household, family, or friendship settings.
- Documented limits, such as a specific spending cap or loan restriction, are more effective than vague promises and should be reviewed regularly.
- Setting boundaries involves mapping your financial relationships, anchoring rules to concrete goals, and planning conversations with scripts to ensure consistency.
- Practicing daily habits like using a pause rule or separating funds helps turn boundaries into sustainable routines.
- Starting with a simple, written rule under 100 dollars or a similar small limit increases the likelihood of long-term adherence.
Table of Contents
- What counts as a money boundary
- Why unclear money boundaries damage relationships and health
- Where money boundaries usually break down first
- A five-step process for boundaries you will actually keep
- Scripts for the conversations you keep avoiding
- Daily exercises that make boundaries stick
- How a structured daily practice turns intentions into habits
- Why boundaries feel harder than they should
- Where to start if you want a structured plan
- Sources
- FAQ
What counts as a money boundary
A money boundary is not a feeling or a general intention to "be better with money." It is a specific limit or agreement that governs a concrete behavior: how much you spend on a category, whether you lend to family, how you split a group bill, or what you are willing to discuss with a coworker. Forbes frames money boundaries as limits around earning, spending, saving, lending, sharing, and discussing money, and the useful ones apply across a range of relationships, not just romantic partnerships.
Common areas where money boundaries matter include:
- Romantic partners, especially around joint versus separate accounts and who covers which bills.
- Friends and roommates, particularly for group spending, shared rent, and casual loans.
- Children and parents, where allowances, chores, and financial teaching moments overlap.
- Extended family, where cross-border or cross-household support requests are common.
- Coworkers and advisers, where discussing salary or accepting financial advice needs limits too.
General boundary taxonomies (physical, emotional, time, and so on) are useful background, but money boundaries deserve their own category because the stakes are measurable and the failure mode is specific: a vague boundary around money almost always resolves into either resentment or a loan you never see repaid.
Why unclear money boundaries damage relationships and health
Money disagreements do more than strain a budget. They erode trust, and the effects follow you outside the conversation itself. Psychology Today's coverage of money boundaries and mental health notes that healthy financial boundaries support dignity and autonomy, and that clear limits help reduce both relationship conflict and mental health harm.
Clear, documented money agreements are more likely to hold than informal promises, according to CFPB guidance on discussing money productively, which recommends setting goals, naming who decides, and recording next steps whenever money comes up between people. That documentation step matters because vague boundaries tend to fail quietly: nobody violated them on purpose, nobody remembers agreeing to anything in the first place.
Three situations show the pattern clearly. Financial infidelity, where one partner hides spending or debt, usually grows out of a boundary that was never made explicit: who reports what, and when. Enabling a family member's spending by repeatedly covering their shortfalls without a stated limit removes any incentive for them to change. And ambiguous group spending, the kind that happens on a weekend trip with no agreed budget, turns a fun plan into a source of lingering irritation because nobody set the rule before the bill arrived.

Where money boundaries usually break down first
Most boundary failures cluster around a handful of predictable situations. Recognizing them in advance makes it easier to set the rule before the pressure hits.
- Household and partner finances: deciding who pays for what, whether accounts stay joint or separate, and how new expenses get approved.
- Group spending and travel: agreeing on a budget and payment method before a trip is booked, not after the hotel bill arrives.
- Family requests, including cross-border support: setting a clear limit on what you can give without resentment, especially with recurring requests from extended family. Anyone budgeting around ongoing obligations, including court-ordered ones, can see how concrete the numbers get with a state child support calculator, which turns a vague sense of obligation into an exact monthly figure.
- Work and client billing: declining to lend money to coworkers, or setting firm terms for late payments if you freelance.
- Casual lending among friends: the request that starts with "just this once" and has no repayment date attached.
A short refusal line works in nearly all of these: "I care about you, and I'm not able to lend money right now. I can help you look at other options instead." The next section turns that kind of line into a repeatable script for harder conversations.
A five-step process for boundaries you will actually keep
Boundaries fail most often because they stay vague: a feeling of being taken advantage of, with no attached number or deadline. The fix is a short, repeatable process that turns a feeling into a rule.
- Map your money circle. List everyone who influences your financial decisions or shares resources with you: a partner, a roommate, a parent, a friend who always asks to split things unevenly. The CFPB Money Circle Toolkit is built for exactly this step, using tools called Money Choices, Money Styles, and Money Network to map influence and responsibility before you set any rule.
- Identify the trigger and attach it to a goal. A boundary without a purpose is just a restriction. Tie it to something concrete: "no unsecured loans to family" protects an emergency fund target; "no more than $50 on takeout weekly" protects a debt payoff date. Experian's guidance on setting financial boundaries recommends identifying your triggers and tying each limit to a specific goal, which makes the boundary easier to defend when someone pushes back.
- Make the rule measurable. Replace "I want to spend less on gifts" with "I will spend no more than $200 total on holiday gifts this year, split across four people." Attach a consequence too: if a shared expense goes over budget, you cover only your agreed share, not the overage.
- Plan the conversation. Before you raise the boundary, prepare the way the CFPB recommends: set an agenda, decide who has the final say on the decision at hand, and keep a neutral tone that describes what you will do rather than what the other person should do. Schedule a specific follow-up point, even if it is just a text in two weeks to check how the new rule is working.
- Enforce and review. Put a recurring reminder on your calendar, monthly or quarterly, to check whether the boundary is holding. If someone violates it, restate the rule once, calmly, and apply the stated consequence rather than renegotiating on the spot.
Pro Tip: Write the rule down somewhere you will see it again, a notes app, a shared budget spreadsheet, a sticky note on the fridge. A boundary that exists only in your head is the easiest one to talk yourself out of.
Scripts for the conversations you keep avoiding
Most people do not struggle with the idea of a money boundary. They struggle with the exact words to say in the moment. A few tested structures cover most situations.
For turning down a loan request, use gratitude, the boundary, and an alternative, in that order: "I appreciate you trusting me with this. I'm not in a position to lend money right now, but I can help you look at a payment plan or a local assistance program." This keeps the relationship intact while closing the door on the specific ask.
For group spending, agree on the number and the payment method before anyone books anything: "Let's cap this trip at $400 per person for lodging and split the group dinner bill evenly, paid through one app so nobody's chasing anyone down afterward." CNBC's reporting on friendships and money points out that ambiguity, not bad intent, causes most of the friction in these situations, so naming the number up front removes the guesswork.
A household money meeting works best with a short, repeatable structure:
- State the purpose: "We're deciding how to split the new car insurance bill."
- Give each person a turn to speak before anyone responds.
- Decide who has the final call if you disagree, or agree to revisit later.
- Recap the agreement out loud: amount, who pays, and by when.
- Set a follow-up date to check whether it is working.
When you feel pressured to answer on the spot, use the pause rule. Experian's guidance on financial boundaries recommends a simple line: "Let me check my budget and get back to you by Thursday." That delay, typically 24 to 72 hours, gives you room to check your goals before you commit to anything.
Daily exercises that make boundaries stick
A boundary you set once in a conversation is fragile. A boundary you practice becomes a habit. A few simple tools help close that gap.
Start by drawing your own Money Circle: a page with your name in the center and lines out to everyone who asks you for money, lends you money, or influences a purchase decision. This visual version of the CFPB's mapping exercise makes it obvious, often within a few minutes, which relationship needs a boundary first.
Pair that with the pause rule for any request or purchase that triggers hesitation. Give yourself 24 to 72 hours before answering a loan request or before buying anything outside your planned budget. The delay is not about saying no by default, it is about removing the pressure of an immediate answer.
A few other tools worth adopting:
- Envelope or virtual-account limits: move your monthly "fun money" or "family support" cap into a separate account so the boundary enforces itself once the balance hits zero.
- Journaling your triggers: a quick note on what preceded an impulse purchase or an uncomfortable lending request helps you spot the pattern, an exercise covered in more detail in our journaling prompts for spending triggers.
- Written agreements for recurring situations: if you regularly split bills with a roommate or lend small amounts to the same family member, put the terms in writing once so you are not renegotiating every time.
- Professional help when boundaries involve debt or legal obligations: a financial counselor or, for support payments, a documented calculation, is worth the cost when informal agreements keep breaking down.
How a structured daily practice turns intentions into habits
Deciding on a boundary is the easy part. Living inside it for a full month, especially when old spending habits are wired to specific triggers, is where most plans fall apart. That gap between intention and daily behavior is exactly what a structured, day-by-day practice is built to close.
A 30-day zero-spend financial reset program can offer:
- Daily challenges that target specific habits like impulse buying and subscription creep.
- Printable trackers to make your spending and savings visible day to day.
- Social scripts for the kind of money conversations covered above.
- Meal planning guides to reduce common sources of untracked daily spending.
Behavioral psychology suggests that habits form through repetition tied to a trigger, not through a single conversation or a single good intention. Converting a boundary from a one-time script into a daily practice, checked against a tracker, is what gives it a real chance of surviving past the first hard week.
Why boundaries feel harder than they should
Setting a money boundary sounds simple until you are the one saying it out loud to a sibling who has always borrowed from you without asking. I have felt that hesitation myself, the small dread before a conversation that should take thirty seconds and instead sits in your stomach for a week.

The boundary that actually worked for me was small: a flat $100 monthly cap on family lending, communicated once, in writing, with no exceptions negotiated in the moment. It was not a dramatic overhaul. It just removed the need to decide, under pressure, every single time someone asked.
Pick one boundary this week. Make it measurable, write it down, and say it once. You do not need all five steps mastered before you start.
, Omar
Where to start if you want a structured plan
If mapping your money circle and writing your first script felt useful, the next step is turning that into daily practice. The 30-Day Zero-Spend Reset Challenge Workbook walks you through the same territory covered above, one day at a time, with trackers and scripts built in so you are not starting from a blank page.
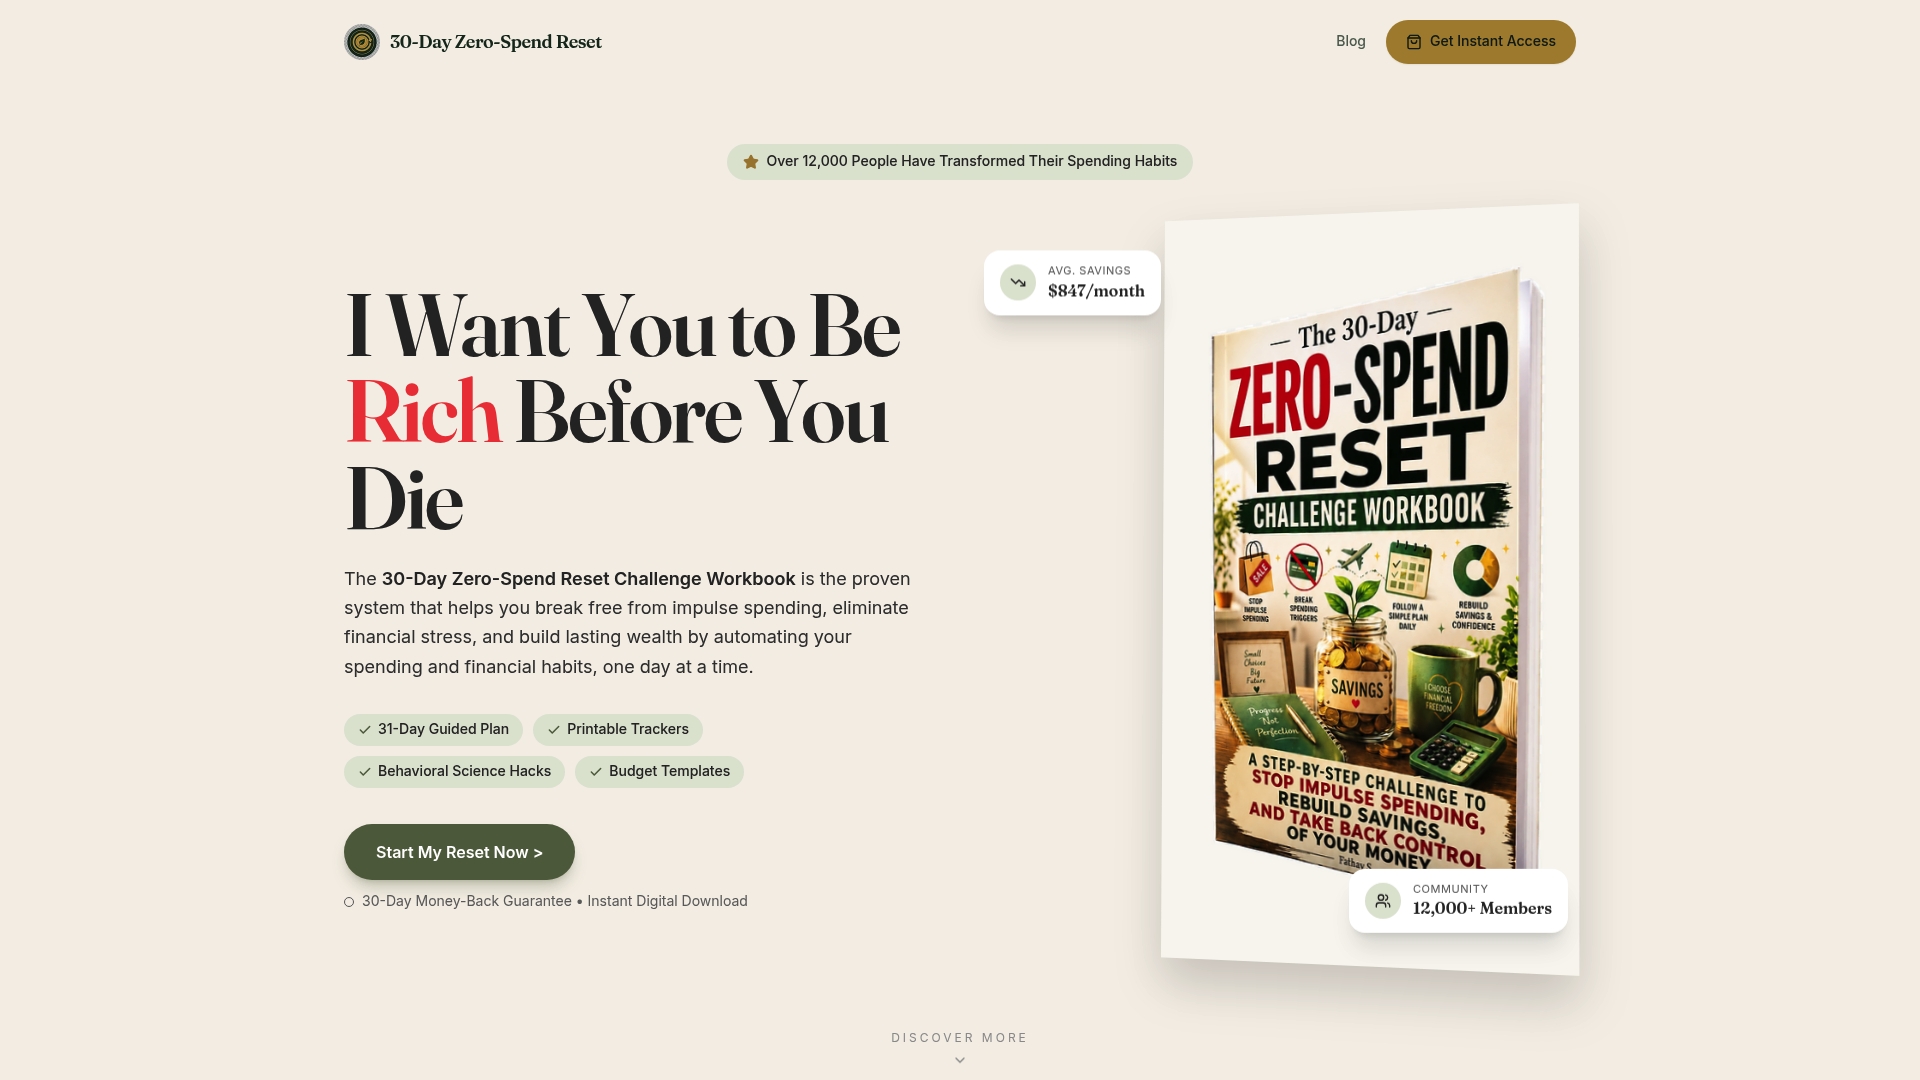
For readers who want the deeper version, with extended trackers and bonus tools layered on top of the base workbook, the Zero-Spend Accelerator Vault bundles those resources together. Either way, the starting point is the same: preview the workbook and pick your first day.
Sources
- Money boundaries that build wealth, confidence and respect, Forbes
- Discussing money productively, CFPB
- 5 ways to set financial boundaries, Experian
- Money boundaries and mental health, Psychology Today
FAQ
What is the 70/20/10 rule for money?
The 70/20/10 rule is a budgeting framework where 70% of income covers everyday spending, 20% goes to savings, and 10% goes to debt repayment or giving. It is one of several percentage-based budgeting rules, alongside the more commonly cited 50/30/20 split, used to anchor spending limits to a plan rather than to guesswork.
What are the 7 types of boundaries?
Common boundary frameworks describe physical, emotional, time, sexual, intellectual, material, and communication boundaries as the main categories people apply across relationships. Money boundaries typically fall under material and communication boundaries, since they govern both possessions and how openly you discuss finances with others.
What is the 3-6-9 rule of money?
Definitions of a "3-6-9 rule" for money vary and are not tied to a single authoritative source, so treat any specific version you encounter with caution. A more reliably sourced anchor for savings goals is the standard emergency fund guidance of setting aside three months to six months of expenses, which pairs well with a measurable money boundary.
What are financial boundaries?
Financial boundaries are specific limits and agreements around how you earn, spend, save, lend, share, and discuss money with yourself and other people. They work best when they are measurable, such as an exact dollar cap or a set response time, rather than a general intention to spend less or say no more often.
Recommended
Ready to reset your spending?
Get the 30-Day Zero-Spend Reset Workbook and turn these ideas into a daily action plan.
Start the 30-Day ResetThis article is part of the 30-Day Zero-Spend Reset method. Explore the complete day-by-day system behind these ideas.
Read the full guideKeep reading


Join the conversation
Be the first to share your thoughts on this article.