
30 Day Plan to Track Cash Spending With Copy Ready Templates

Use a 30 day habit first plan to track cash spending with copy ready logs, daily prompts, and templates. No app required.
30 Day Plan to Track Cash Spending With Copy Ready Templates
The most reliable way to track cash spending is to capture every purchase the moment it happens, using a receipt, envelope, or quick note, then review the totals weekly and summarize them after one month. Success looks like a clear set of category totals that points to at least one place where you can cut or redirect money.
TL;DR:
- Tracking cash spending consistently requires capturing each purchase immediately using receipts, notes, or photos to avoid memory gaps.
- Weekly totals should be aggregated into a monthly summary, accounting for irregular expenses and comparing against planned budgets for better financial planning.
- Categorizing expenses into needs, wants, and obligations helps identify areas for cost reduction, especially in wants, which are easiest to trim.
- A simple log with four fields per transaction or a spreadsheet with formulas automates the process, making recurring tracking straightforward and less time-consuming.
- Using a guided 30-day reset challenge or a built-in workbook can help reinforce the habit for those who struggle with DIY systems or lose momentum.
Table of Contents
- Practical ways to capture cash purchases as they happen
- A simple daily routine to follow for 30 days
- Turning weekly entries into a monthly spending picture
- Sorting cash spending into needs, wants, and obligations
- Copy-ready templates for logging and summarizing cash
- Fixing the most common tracking slip-ups
- When a guided reset beats building your own system
- How the 30-Day Zero-Spend Reset Challenge Workbook fits alongside manual tracking
- FAQ
- Sources
Practical ways to capture cash purchases as they happen
The method you pick matters less than whether you actually use it. Pick the one that fits how you already move through your day.
The envelope or receipt-jar method works well if you pay cash often and already get paper receipts. Keep one envelope per week, or label separate envelopes by category like groceries, dining, and gas, and drop every receipt in immediately. When you have no receipt, jot the amount and purpose directly on a scrap of paper and toss it in too. This manual capture habit, collecting receipts and filling in missing details right away, avoids the memory gaps that sink most tracking attempts.

A pocket notebook works for people who buy things where receipts are rare, like tips, vending machines, or street vendors. Write the date, amount, and a two-word description the instant you hand over cash. The goal is friction-free capture, not a tidy ledger.
If you always have your phone out anyway, a quick note app, a voice memo, or a photo of the receipt does the same job digitally. Some people snap every receipt into a single photo album and sort it later.
- Envelope or receipt jar: best for frequent cash users who already collect paper receipts.
- Pocket notebook: best when receipts are rare or nonexistent.
- Phone notes, voice memos, or photos: best for people glued to their phones anyway.
- Apps with manual entry: good for built-in search and totals, but they cost you a few seconds of typing per purchase.
The CFPB's spending tracker recommends exactly this: collect receipts, write in missing details, and total them by category weekly, which turns scattered scraps into a usable, monthly summary.
A simple daily routine to follow for 30 days
A routine only works if it takes seconds, not minutes. Here is a minimal version you can keep up for about a month.
- At the moment of purchase, grab the receipt or jot the date, amount, and category on paper.
- At the end of each day, drop loose receipts into your envelope or photograph them into one album.
- At the end of each week, transfer every entry into a simple log with four fields: date, amount, category, and a short note (payment method is optional but helpful).
- After one week, scan your log for gaps. Did you miss a day? Add a reminder, like a sticky note on your wallet, and keep going.
Pro Tip: Set a recurring phone alarm for 8 p.m. labeled "receipts," so the end-of-day consolidation becomes automatic instead of optional.
The CFPB notes that tracking a full month, rather than a week or two, captures irregular expenses like subscription renewals or quarterly bills that shorter windows miss entirely.
Turning weekly entries into a monthly spending picture
Weekly totals only matter once you combine them into a financial management plan that guides your monthly decisions. At the end of each week, add up what you spent per category, then carry those subtotals into a single monthly summary sheet.
- Add each week's category subtotals together to get a monthly figure per category.
- Watch for one-time or irregular costs, like an annual membership or a quarterly insurance payment, that can distort a single week's numbers.
- Compare your monthly totals against what you planned to spend, and flag any category that ran over.
- Pick one specific change for next month, like a lower dining-out cap or a canceled subscription, instead of trying to fix everything at once.
The FDIC frames this as a shift from recording history to planning ahead: the review itself is what turns a month of logging into a better plan for the next one.
Sorting cash spending into needs, wants, and obligations
Categorizing your spending gives the numbers meaning. Needs are costs you can't skip, like groceries or transportation to work. Wants are optional, like takeout coffee or impulse buys. Obligations are recurring commitments, like a gym membership or a subscription you agreed to.
When a purchase sits in a gray area, ask whether skipping it next month would meaningfully disrupt your life. If not, it's a want.
- Needs: keep as-is, but look for cheaper substitutes before cutting.
- Wants: the first place to trim since cuts here cost the least adjustment.
- Obligations: review for renegotiation or cancellation, especially subscriptions you forgot about.
- Savings: treat as its own required category, not what's left over after everything else.
The CFPB specifically recommends converting savings into a fixed line item, which makes it far more likely to actually happen.
Copy-ready templates for logging and summarizing cash
You don't need special software to track cash well. A per-transaction log needs four columns: date, amount, category, and note. A weekly summary table rolls those entries into category columns with a total row at the bottom.
| Category | Week 1 | Week 2 | Week 3 | Week 4 | Monthly total | |---|---|---|---|---|---| | Groceries | $42 | $38 | $51 | $45 | $176 | | Dining out | $25 | $30 | $18 | $22 | $95 | | Transportation | $20 | $15 | $25 | $20 | $80 |
If you use a spreadsheet, one SUMIF formula automates the category totals: list every transaction with a category column and an amount column, then use something like SUMIF(category range, "Groceries", amount range) to pull the total automatically. For irregular income or shared expenses, add a column marking who paid or which pay period the cash came from, so totals stay accurate even when your income doesn't arrive on a fixed schedule.
Fixing the most common tracking slip-ups
Most people don't quit tracking because the method fails. They quit because one missed day turns into a week of silence. Here's how to recover fast.
- If you forget a receipt, reconstruct it from memory within 24 hours, before the details fade, and mark it as estimated.
- If daily capture falls apart, run a 10-minute weekly catch-up session instead of abandoning the log entirely.
- For impulse buys, try a visible cash jar for discretionary spending or a 24-hour delay rule before any non-essential purchase.
- Recruit a partner or friend for light accountability, or set a small reward for finishing a full week of consistent logging.
Pro Tip: Keep the conversation about money low-pressure. Our social scripts for money conversations can help if talking about cash spending with a partner feels awkward.
When a guided reset beats building your own system
Manual tracking works, but it asks you to design the habit, the categories, and the motivation all at once. A behavior-first 30-day structure removes that design work, which is why it tends to stick better for people who've abandoned spreadsheets before. It helps most if you've tried tracking solo and lost momentum by week two. Whatever method you choose, let the numbers guide your next decision rather than becoming a source of guilt.
, Omar
How the 30-Day Zero-Spend Reset Challenge Workbook fits alongside manual tracking
Everything above works on its own, but it asks you to build the structure yourself: the templates, the daily prompts, the reminders to keep going when week two gets tedious. The 30-Day Zero-Spend Reset Challenge Workbook hands you that structure already built, with daily behavioral challenges, printable trackers, budget templates, and a companion webapp that logs prompts alongside your spending entries.
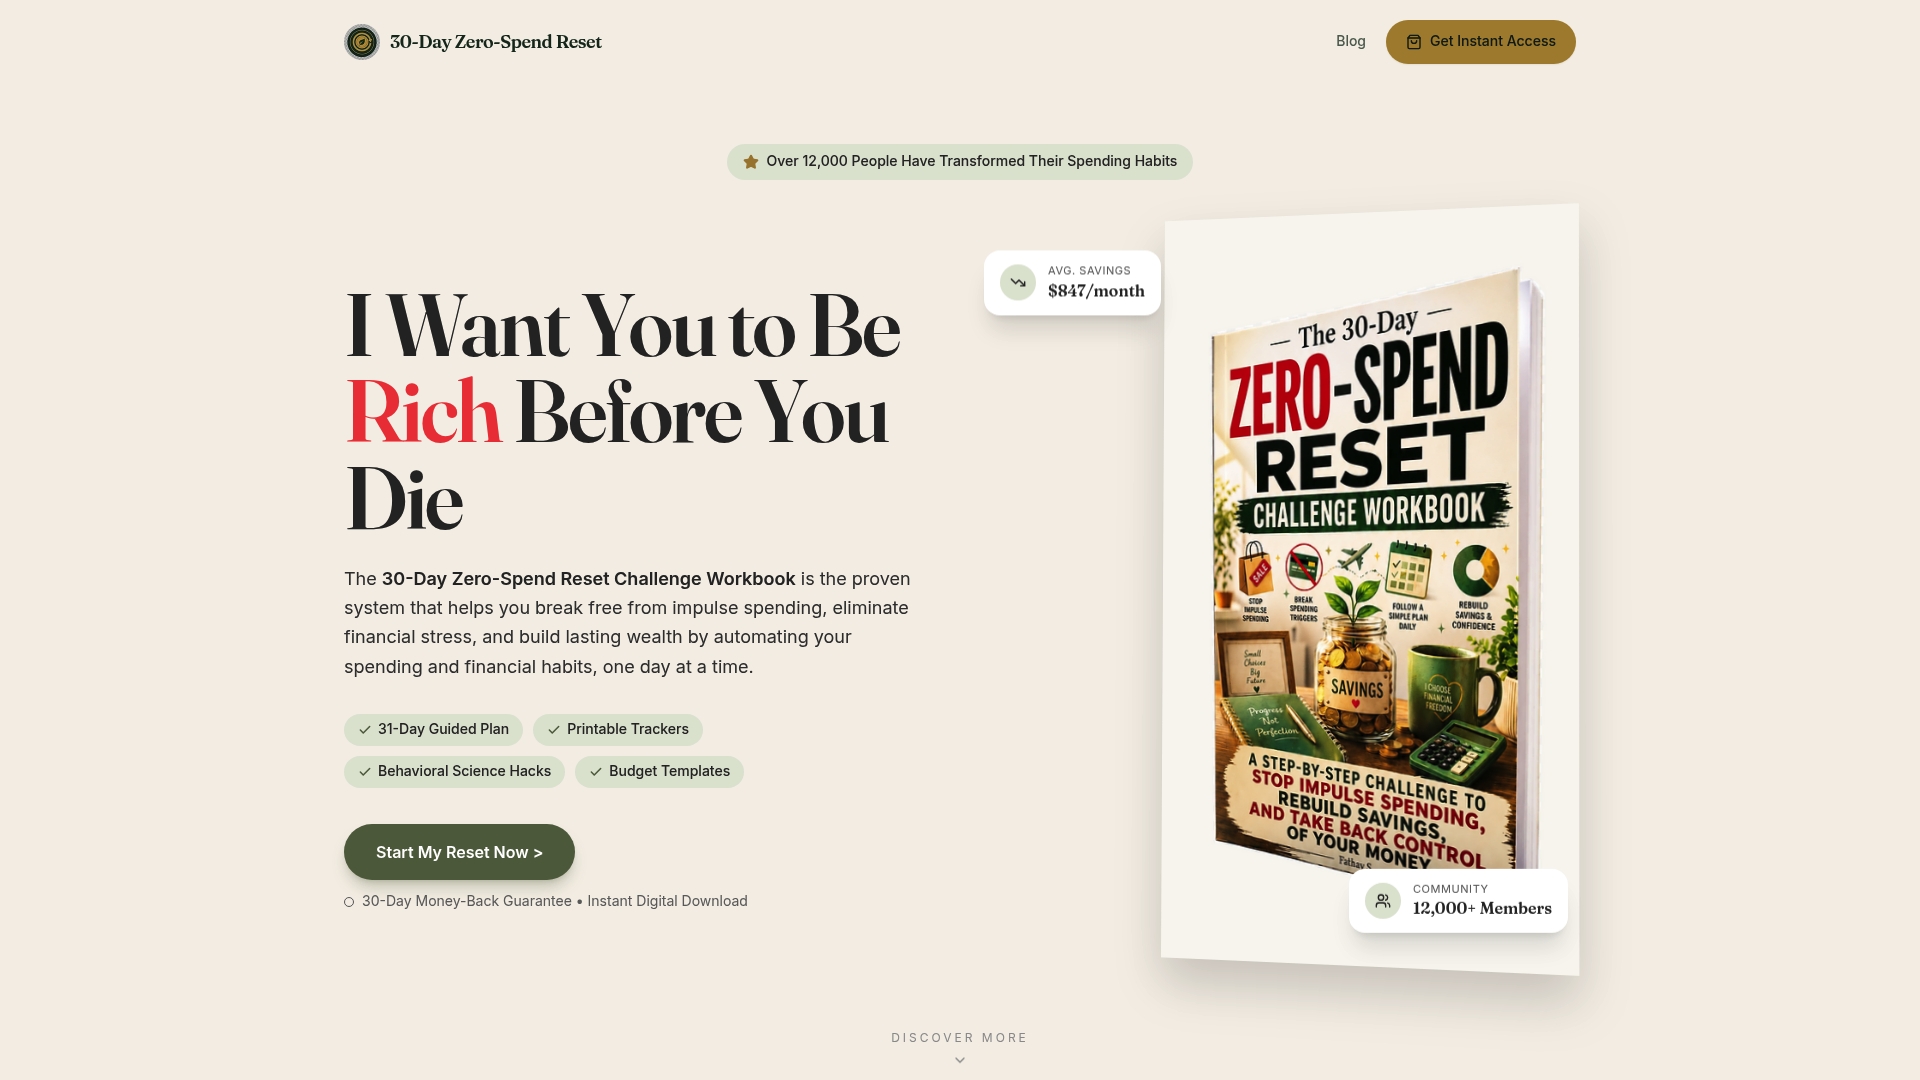
It's built to supplement exactly the kind of manual capture we've walked through here, adding daily behavioral prompts so tracking doesn't quietly stop being a habit. For readers managing food costs on top of spending habits, the workbook also includes meal planning guides. If you want a deeper toolkit after your first reset, the Zero-Spend Accelerator Vault extends the same system with additional resources. Start with the 30-Day Zero-Spend Reset Challenge Workbook and build your first full month of tracked, categorized cash spending.
FAQ
What is the best money spending tracker?
The best tracker is whichever one you'll actually use every day, whether that's a paper envelope system, a notebook, or a spreadsheet with manual entry. The CFPB's free spending tracker offers a simple fillable template built around the same receipt-and-category method described above.
Can you live off $1,000 a month after bills?
This depends entirely on your remaining fixed costs, location, and household size, so there's no universal answer. A spending-and-saving plan that compares your net income against your actual expenses, as outlined in FDIC's budgeting guidance, is the most reliable way to find out for your specific situation.
What is the 70/20/10 rule for money?
Definitions vary across sources, but a common version splits income into 70% for living expenses, 20% for savings, and 10% for debt repayment or giving. It's a rough allocation framework rather than a fixed rule, and your own needs-versus-wants breakdown from tracked spending will tell you whether it fits your situation.
Can you save $10,000 in 3 months?
Saving that amount in three months would require a high income relative to expenses or a major one-time cut in spending, so it isn't realistic for most households on typical budgets. Tracking your cash spending for one full month, as recommended by the CFPB, is the first step to finding out how much you can actually redirect toward savings each month.
Sources
Start with the CFPB's spending tracker tool and the FDIC's saving and planning guidance for free, official templates.
- Track your spending with this easy tool, Consumer Financial Protection Bureau (CFPB)
- Spending tracker, CFPB
- Money Smart for Young Adults: Spending and saving plan, FDIC
- FDIC consumer resource: saving, unexpected expenses, and your future
Recommended
Ready to reset your spending?
Get the 30-Day Zero-Spend Reset Workbook and turn these ideas into a daily action plan.
Start the 30-Day ResetThis article is part of the 30-Day Zero-Spend Reset method. Explore the complete day-by-day system behind these ideas.
Read the full guideKeep reading



Join the conversation
Be the first to share your thoughts on this article.